Our comments supporting the two-year sustainment clock while pressing for investor safeguards on third-party promoter liability, source-of-funds burdens, bridge financing, and retroactivity. If USCIS ignores these recommendations without justification, we are prepared to sue under the Administrative Procedure Act.
Since our founding, we have assiduously defended the interests of investors against hostile policy changes, such as efforts to extend the EB-5 sustainment period and beyond.
Our defense of investor interest is not merely reactive, but proactive. Hence, we seek to actively contribute to policy changes in immigration law, whether through legislation in Congress or regulation by USCIS, that will advance the interests of investors. Our objectives are to reduce processing times for petitions and ensure investors can reobtain investment capital as quickly as possible.
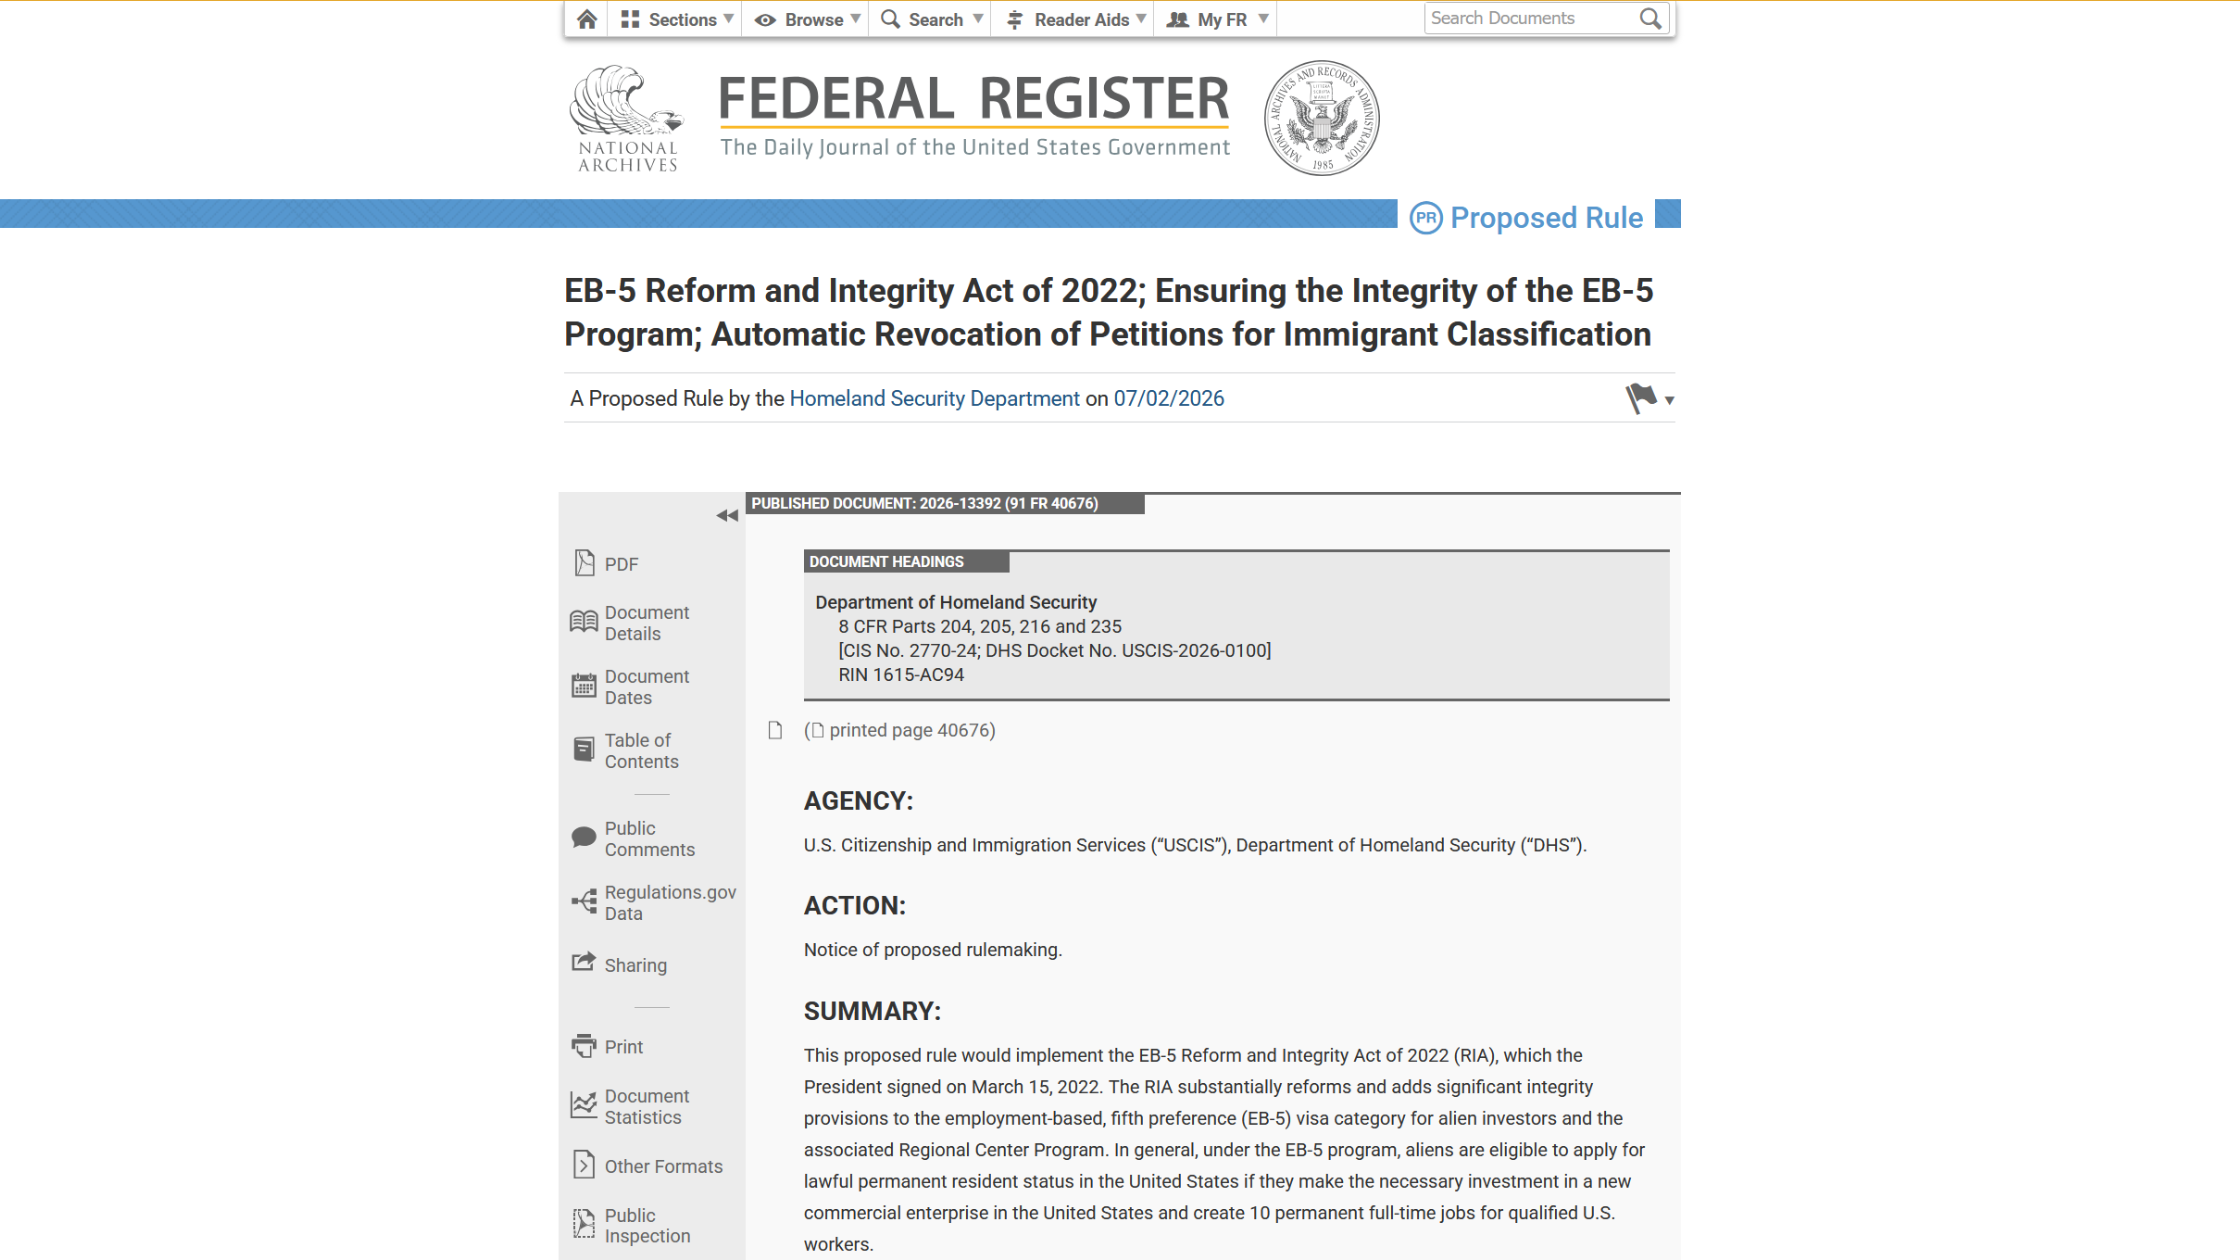
To this end, AIIA recently submitted comments in response to USCIS’s Notice of Proposed Rulemaking (NPRM) regarding new EB-5 program rules, promulgated pursuant to the EB-5 Reform and Integrity Act (RIA) of 2022. The rules were issued by the second Trump administration this year to govern the program.
AIIA analyzed the proposed rule in detail and relied upon legal advice from experts. We broadly support the new rules and commend the administration for its work. In particular, we applaud the specification of a two-year sustainment period beginning the moment capital is placed at-risk. This was a key reform of the RIA, which regional centers have frivolously sued to overturn.
For other provisions of the NPRM, AIIA has provided USCIS with helpful feedback that seeks to shape these rules for the benefit of investors. Under the Administrative Procedure Act, USCIS must read these comments and either incorporate their recommendations into the final rule or explain their absence. Failure to do so will mean AIIA has the ability to block any anti-investor provisions by suing USCIS under 5 U.S.C. § 706.
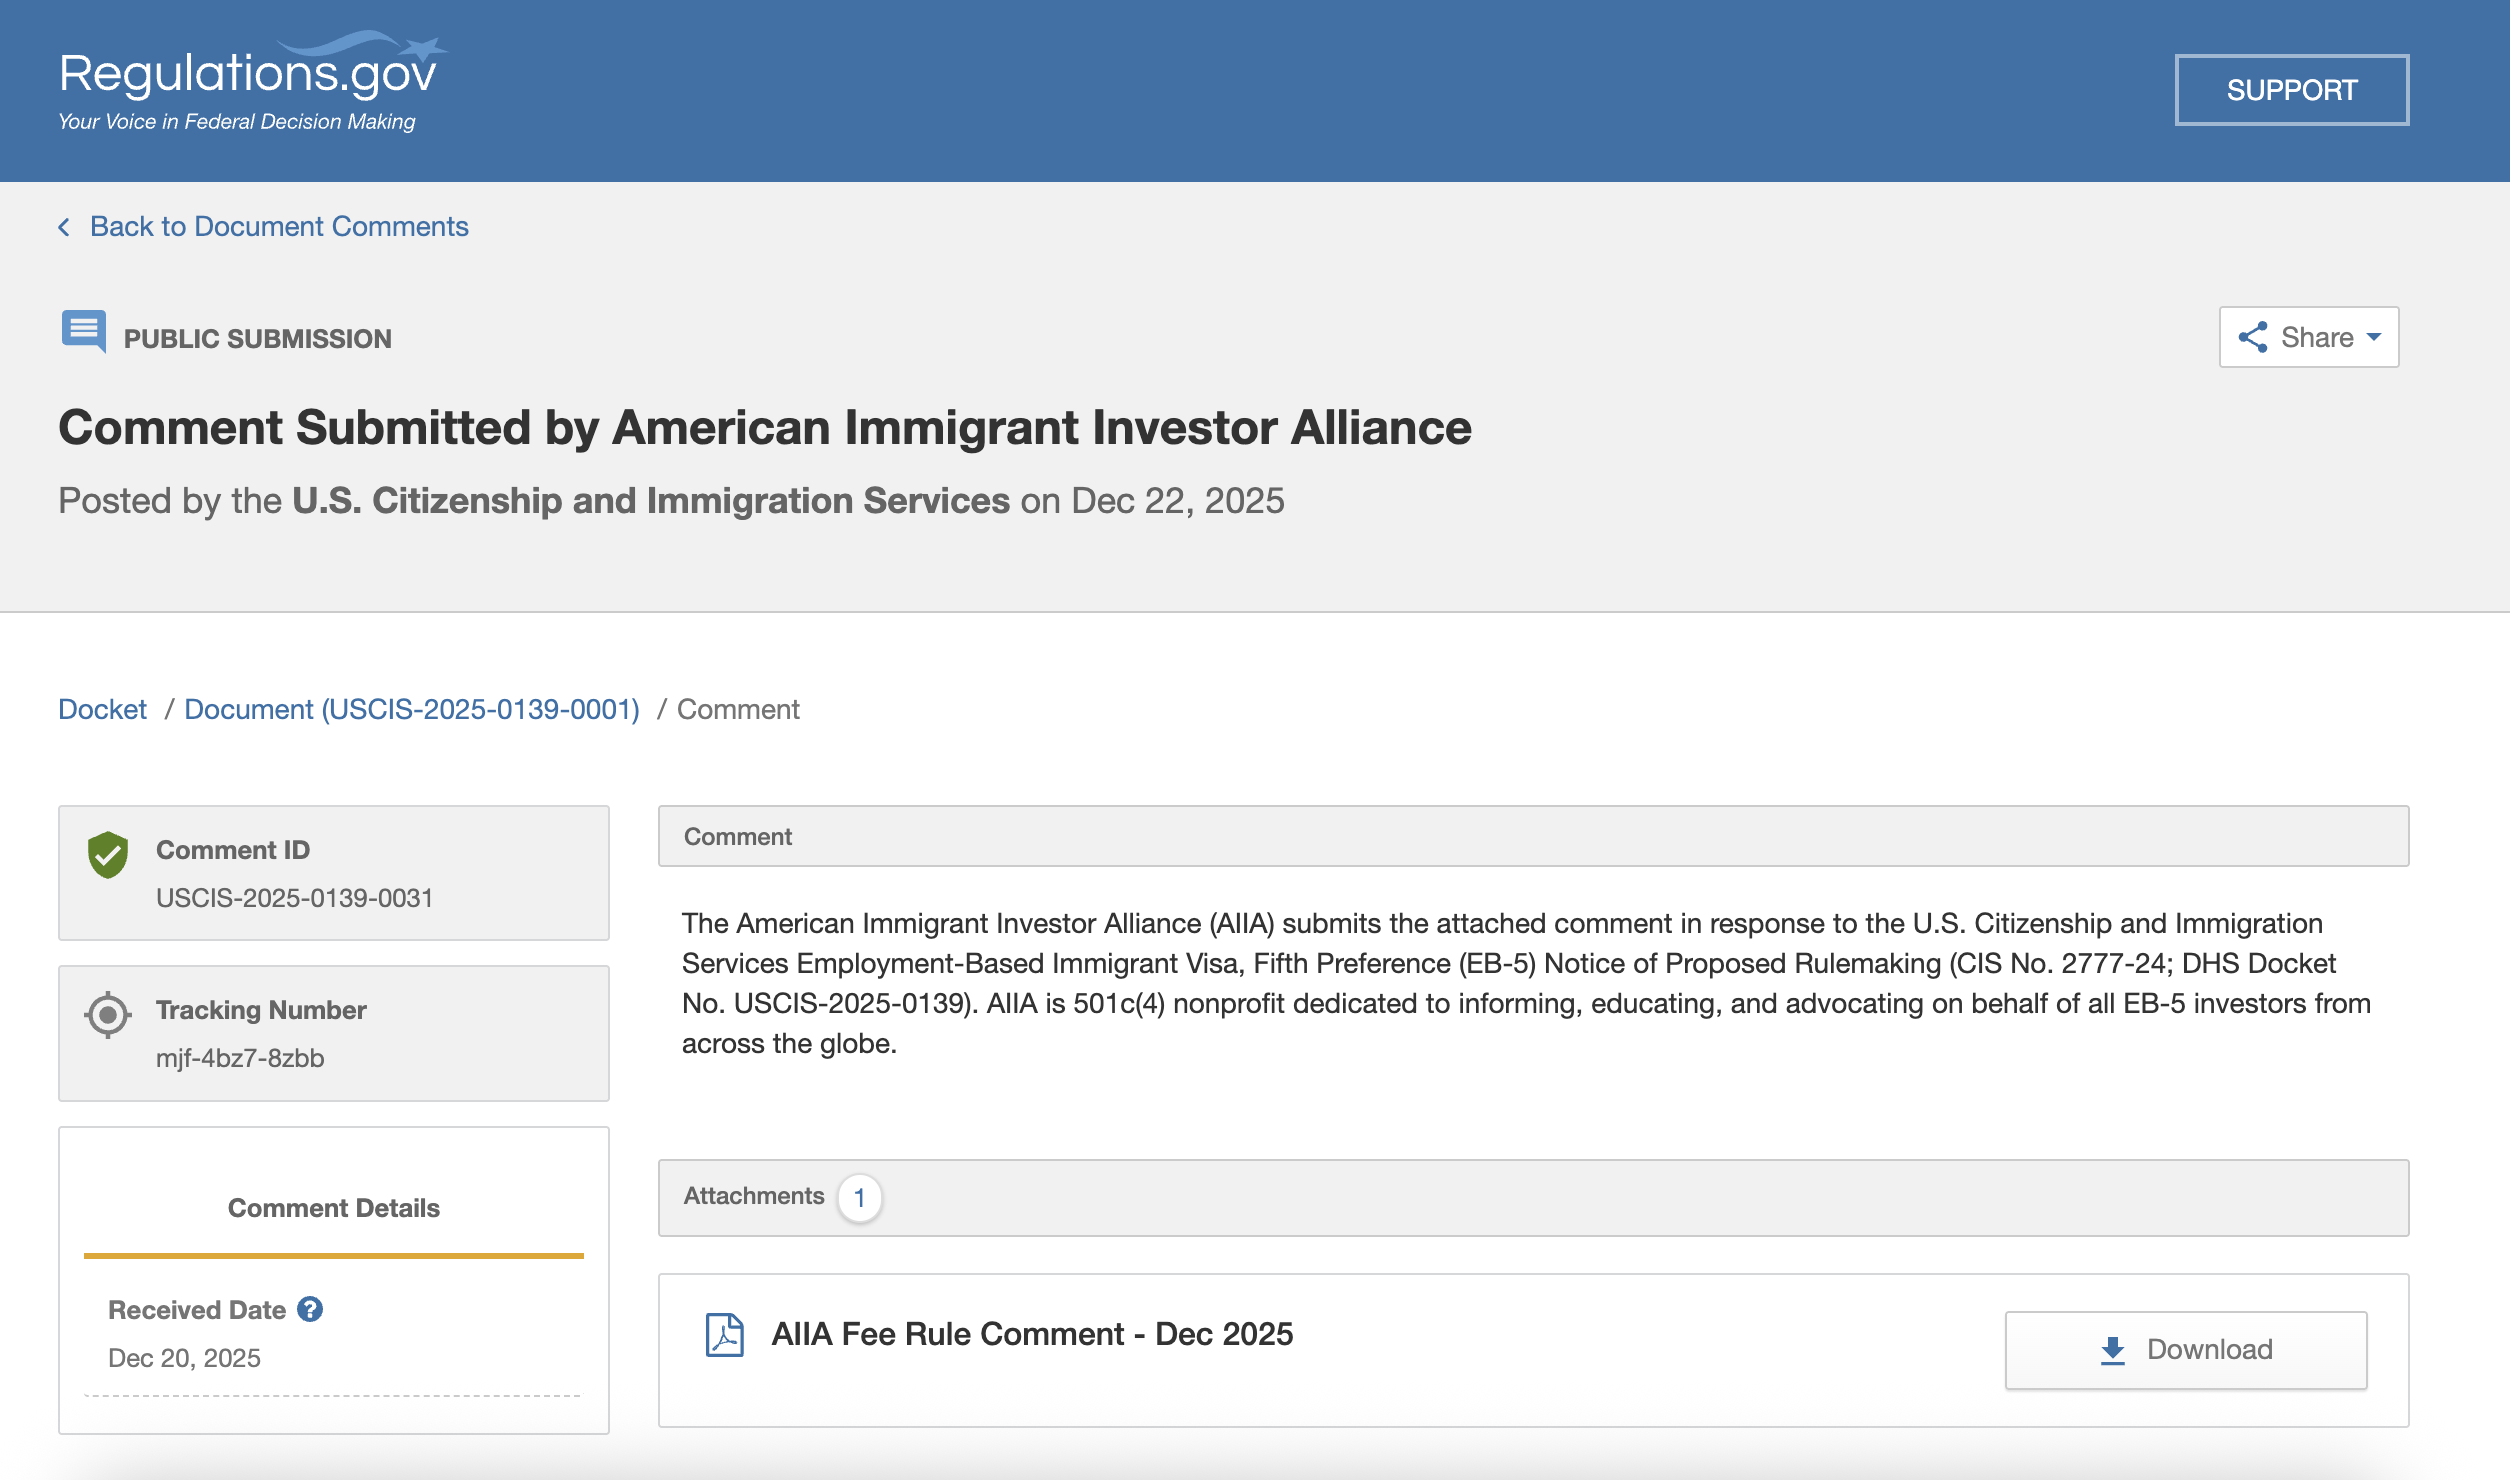
Our feedback covers six provisions of the NPRM, the summaries of which are set forth below. You can also read our full comment here.
1. Specifying the Sustainment Period
The new rules helpfully restate the RIA’s provisions that capital must be sustained at-risk for a minimum period of two years, which differs from the pre-RIA requirements of sustainment for two years after the grant of conditional Lawful Permanent Resident (LPR) status. See 8 U.S.C. § 1153(b)(5)(A)(i) (“capital…is expected to remain invested for not less than 2 years”). The new rules expressly codify the intent of Congress that such a period begin immediately once capital is placed at-risk in a new commercial enterprise (NCE). Anyone who argues to the contrary is wrong.
However, there are some ambiguities in the new rules that AIIA seeks to clarify. Specifically, the rules do not exactly specify when the two-year period is to begin: whether upon receipt by the NCE, release from escrow, disbursement to the job-creating entity (JCE), or the JCE’s spending of capital to create jobs. There is often a significant gap in time between each of these steps. AIIA wants the two-year clock to begin as early as possible.
Hence, AIIA has recommended that USCIS rewrite the rule to specify that the two-year sustainment period’s clock begins at the moment capital is irrevocably contributed to the NCE, provided that it remains available to the JCE (even though the JCE may actually only receive the capital later). The clock should not depend on when the JCE spends the capital. AIIA has recommended the earliest date that is reasonable for the two-year clock to begin, which will benefit investors by ensuring their sustainment requirement is completed as early as possible.
2. Third-party Promoters and Form I-956K
One of the biggest integrity issues with the EB-5 program that adversely affects investors is the existence of fraudulent third-party promoters in foreign countries. These promoters often use misleading advertisements to lure unsuspecting investors into making large capital transactions to them, on the pretext of participating in the EB-5 process. Often, these promoters lie about the program’s rules and requirements to make the investment seem more financially attractive than permissible by statute.
In the domestic United States, such fraudulent promotion would be curtailed by federal securities laws, under the Securities Exchange Act of 1934 that is enforced by the U.S. Securities and Exchange Commission (SEC) and subsidiary private bodies like the Financial Industry Regulatory Authority (FINRA). At present, USCIS requires domestic third-party promoters to fill Form I-956K in order to lawfully promote EB-5 opportunities, which allows for their regulation and oversight. However, because many fraudulent third-party promoters are foreign nationals in foreign countries, they are beyond the jurisdiction of the United States and cannot be easily prevented from false offerings.
An EB-5 petition that is predicated on fraud or misrepresentation may be revoked by USCIS, which then terminates or forecloses any immigration benefits to the investor and their dependents. Under the language of the rule, such revocation may occur due to fraudulent conduct by the foreign third-party promoters alone, even when the investor is innocent of any malfeasance and is unaware of such conduct. AIIA does not want investors to lose immigration benefits under any circumstance, especially when they have done nothing wrong.
Hence, AIIA has recommended that USCIS rewrite the rule to ensure that no petition is revoked due to misconduct by a third-party promoter alone. If fraud is detected, an investor should be provided with notice and an opportunity to course correct. AIIA has also made a technical recommendation that USCIS not duplicate the requirements of Forms I-956H and Forms I-956K.
3. Protecting Investors Who Are Limited Partners in a Project
Often, EB-5 regional centers and NCEs are incorporated as limited partnerships, with some of the partners being EB-5 investors themselves. This is permissible under the EB-5 Regional Center Program, which permits passive investments rather than active investments where an EB-5 investor is a general/managing partner.
However, under the new rules, any person with a stake in the partnership may be regarded as a “person involved” in an EB-5 project. Normally, this would require them to file Form I-956H, to establish their bona fides before USCIS. AIIA is concerned that EB-5 investors who anyway must file Form I-526E may be subject to duplicative requirements with Form I-956H. They may be required to undergo fresh background checks and biometric screening that are redundant. In any case, as limited partners, EB-5 investors will have no direct authority to control how investments are used, which means such requirements are unnecessary.
Therefore, AIIA has recommended that USCIS modify the final rule to specify that only persons with direct authority over a partnership’s pooling, investment, release, acceptance, control, or use of Regional Center Program funds be required to file Form I-956H. This would exempt EB-5 investors who are limited partners, even if they have customary voting rights in a partnership. It would reduce investors’ administrative burdens.
4. Limiting “Source of Funds” Evidence to EB-5 Capital in a Project
The proposed rule requires that any NCE with multiple owners be only capitalized with funds derived by lawful means in order to be EB-5 eligible. If a project cannot establish a lawful source of funds, then the capital must be replaced and the NCE can be subject to sanctions. The rule states that individual investors must identify non-EB-5 sources of funding, while the regional center must prove the lawfulness of funds from these sources. The requirement is intended to prevent money laundering.
Under this requirement, an investor’s petition could only be approved subject to a regional center proving that all funds have been lawfully derived. This is a very onerous requirement that is unfair to investors. Often, NCEs use non-EB-5 capital from domestic U.S. investors to cover project costs. An investor often cannot compel these domestic capital owners to provide upstream evidence to prove the lawfulness of their funding sources, which may be withheld for privacy reasons. Regional centers lack the incentive to aggressively demand such evidence from non-EB-5 investors, since they receive commissions upon capital being deposited and, per se, are financially unaffected even if an EB-5 investor does not receive LPR status.
AIIA has thus recommended that USCIS rewrite the rule to limit the obligations on investors. Specifically, we propose that non-EB-5 investors only be required to provide a basic identification of non EB-5 sources, with any Requests for Evidence (RFE) or adverse action on a petition only if USCIS has a particular reason to believe the other funds were unlawfully derived. We also propose safe harbors for investors if evidence of the lawfulness of a project’s non-EB-5 funding cannot be provided, as well as opportunities to cure any issues of unlawfulness. A good-faith investor should not be denied based on third-party capital outside the investor’s knowledge and control.
5. Removing the Prohibition on Bridge Financing
An EB-5 project is generally long and USCIS processing times for I-526/I-526E petitions are even longer. The delays in the process cost money to projects. Land acquisition, construction, and draw schedules cannot afford to wait for the EB-5 fundraising process that aggregates capital in the NCE.
Under longstanding practice, projects employ the use of “bridge financing” or other funds that temporarily capitalize a project to spend money on its completion. EB-5 funding comes later and replaces the bridge financing. Any jobs created by funding that EB-5 capital replaces are attributed to an investor’s contribution, and satisfy the job creation requirements of the program that allow for LPR status. USCIS’s new rule, however, would ban the use of such bridge financing and require EB-5 capital to be actually spent on job creation.
The rule would make many projects uneconomical, discourage EB-5 investment, dramatically increase the completion time of projects, and create less jobs. AIIA has advised USCIS to delete this provision. Instead, we have recommended that USCIS adopt limits on bridge financing as a percentage of total project cost and some regulations on how such financing may be obtained. Bridge financing cannot be eliminated as it is necessary to ensure the viability of the EB-5 program.
6. The Effective Date of the Proposed Rule
The new rule states that its provisions will apply prospectively to petitions and applications filed on or after the final rule’s effective date. There are six exceptions provided. However, there is conflicting language in the rule that would appear to apply all provisions to all EB-5 petitions filed after the RIA was enacted on March 15, 2022.
AIIA strongly opposes the latter outcome. EB-5 petitions should be subject to the same standards that were in force at the time they were filed, rather than new substantive changes to the program later. Retrospective changes may impose legal, financial, and personal burdens on investors. They will also likely increase the time taken to adjudicate petitions as USCIS adjusts to the new requirements. These are known as “reliance interests” that are legally significant and often considered by courts in civil actions. USCIS should not discount them. Here, they are heavy.
AIIA has recommended that USCIS clarify this language in the rule by specifying uniformly throughout the document that the new provisions only apply prospectively to petitions filed after the final rule takes effect.
Conclusion
The aforementioned recommendations may not be adopted by USCIS, either in whole or in part. Nevertheless, AIIA has a duty to submit them in the interests of investor protection. As noted, if USCIS does not adopt a submitted recommendation and does not provide a valid justification for doing so, AIIA can sue USCIS to block the rule from taking effect, under the Administrative Procedure Act (APA), by arguing that it is “arbitrary and capricious.” This is a tried-and-tested legal tactic that is routinely practiced by advocacy groups, especially regarding immigration policy.
In all likelihood, litigation will ensue after the rule is adopted, regardless of its provisions. Even if investor interests are satisfied, other EB-5 stakeholders such as regional centers may oppose pro-investor provisions, e.g., on sustainment, and sue under the APA to block the rule.
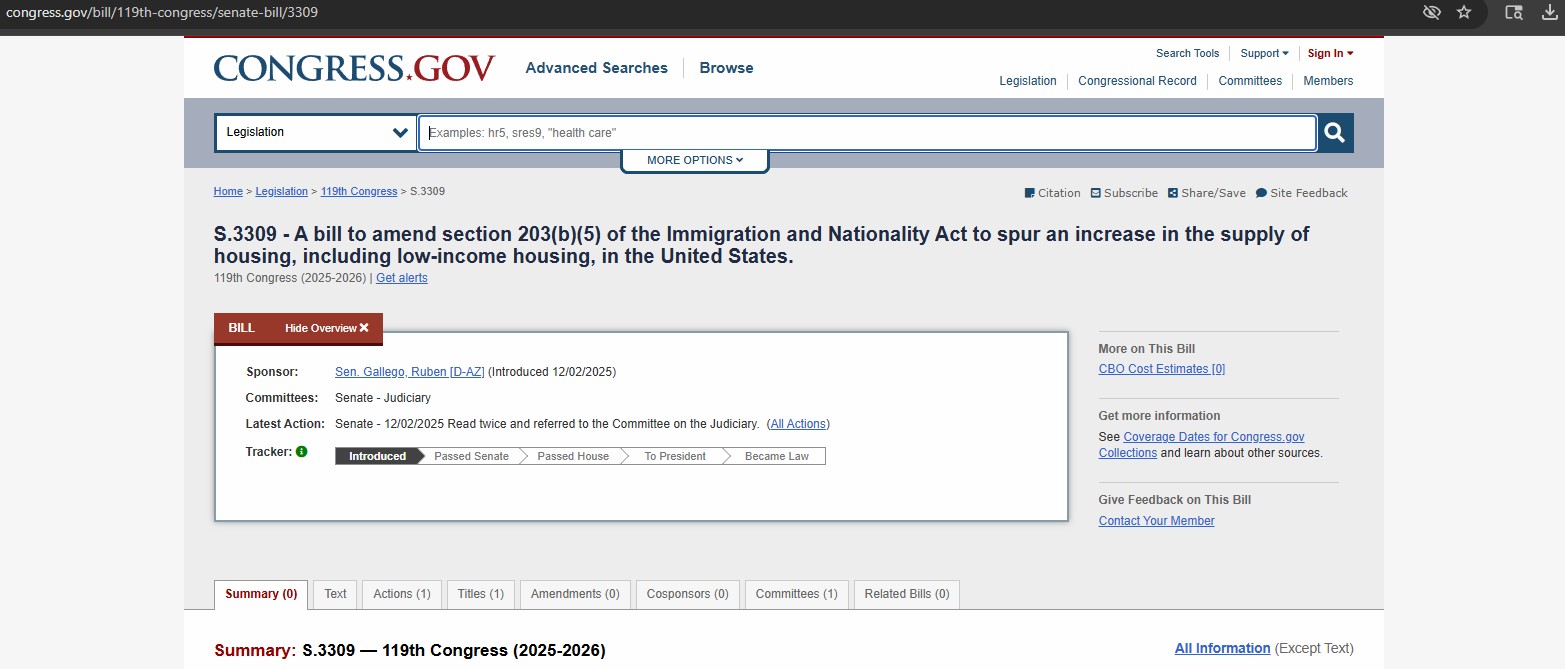
Hence, AIIA is preparing itself for a legal fight to defend pro-investor provisions in the rule. We are simultaneously waging a political fight to have Congress codify these pro-investor provisions into the text of the Immigration and Nationality Act when the EB-5 program must be reauthorized in 2027. If litigation is intense, these two efforts may merge, whereby we lobby Congress to enact provisions that are being litigated by hostile parties, so as to foreclose their claims and secure investor interests in law.
All of these efforts are expensive. AIIA is the only organization advocating on behalf of EB-5 investors in the United States. We rely on donations for our work. If you wish to support us, please 向 AIIA 捐款 或 become a member of our Alliance 今天。.

了解 AIIA 的最新动态
加入我们的时事通讯,了解 EB-5 的最新动态。.
一旦订阅,即表示您同意我们的隐私政策,并同意接收本公司的更新信息。
推荐资源
最近的博客文章
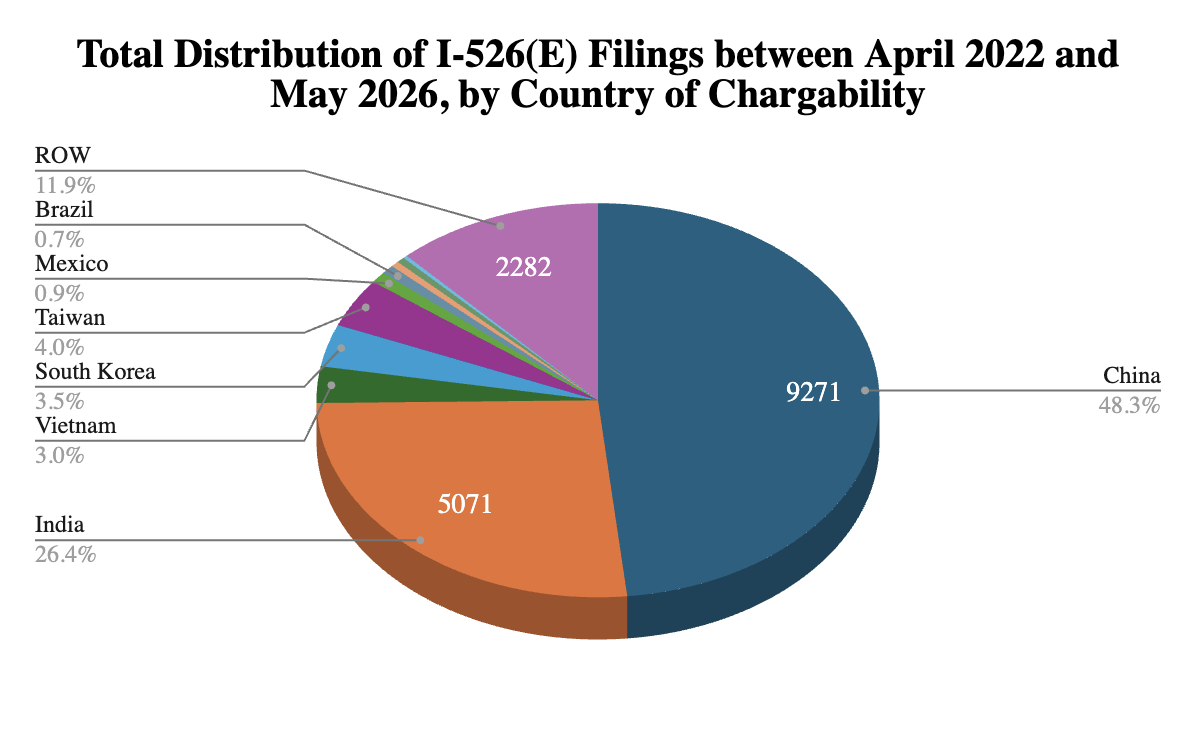
AIIA FOIA Series: Updated I-526E Inventory Statistics for May 2026
Investors from India and China still face significant visa backlogs regardless of category, Korea, Taiwan and Vietnam are still investing...
了解更多
The Administration is Attacking EB-5 by Wasting Visa Numbers through an RFE Debacle
USCIS is deliberately issuing baseless, repetitive RFEs demanding already-submitted Form I-693 medical exams from EB-5 and other employment-based adjustment applicants,...
了解更多
Class Action Lawsuit Filed Against USCIS for EB-5 Fee Refunds
Did you pay inflated EB-5 filing fees after April 2024? AIIA has filed a federal class action lawsuit against USCIS...
了解更多
AIIA FOIA 系列:2025 年 7 月 I-526E 清单最新统计数据
AIIA 获得了截至 2025 年 7 月 31 日的最新 FOIA 数据,这些数据揭示了美国公民与移民服务局(USCIS)实际处理 EB-5 申请的方式,显示了严重的优先排序...
了解更多联系我们
如果您有任何问题、咨询或合作建议,请随时联系我们。
 Chinese
 English
 Vietnamese
答复 (0)